What Happens To Your Private Pension When You Die Gov
Ever wondered what happens to your private pension when you kick the bucket? It's not as morbid as it sounds, promise! Let's dive in, shall we?
When You're Still Kicking
First things first, your pension is all yours while you're alive and well. You've been paying into it, after all. It's like your very own little nest egg, growing and growing.
But what if you need some of that cash before you retire? No worries! You can usually withdraw some of it, but beware the taxman - he'll want his share.
Must Read
When You're No Longer With Us
Alright, let's get real for a sec. When you're gone, your pension doesn't just vanish into thin air. It depends on the type of pension you've got.
Defined Contribution Pensions
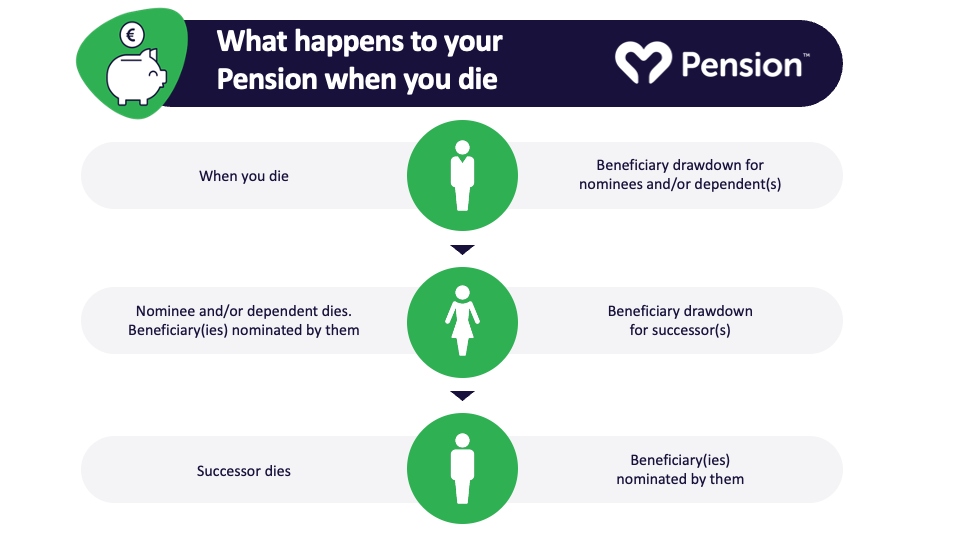
These are the most common types. Your pension pot is invested, and its value can go up and down. When you die, whatever's left goes to your nominated beneficiary. That's right, you get to choose who gets your hard-earned cash!
But here's where it gets interesting. If you die before you retire, your beneficiary could get a tax-free lump sum. How's that for a parting gift?
Defined Benefit Pensions
These are less common, but they promise a regular income when you retire. When you die, your beneficiary might get a lump sum or an income for life. But here's the kicker - if you die young, your pension could be worth more than your house!
Seriously! A 25-year-old with a £10,000 a year pension could leave behind a £500,000 pot if they die young. Now that's an inheritance!
What If You Haven't Nominated a Beneficiary?
Don't worry, your pension won't disappear. It'll go to your estate, and your executor will sort it out according to your will. But here's a fun fact - if you die intestate (without a will), your pension could go to someone you never intended to inherit!
So, it's always a good idea to keep your pension up to date with your latest wishes. It's not the most exciting task, but it sure beats leaving your hard-earned cash to your ex!

Death Benefits and Tax
Death benefits from pensions are usually tax-free, but there are limits. If your pension pot is worth more than the lifetime allowance (currently £1,073,100), your beneficiary might have to pay some tax.
But don't let that put you off saving for your retirement. After all, it's better to have a big pension pot and pay some tax than to not have enough to live on!
So, What's the Moral of the Story?
Your pension doesn't disappear when you do. It's an important part of your estate, and it's worth thinking about who you want to inherit it. It's not the most fun topic, but it's a important one.
And who knows, you might even enjoy learning about pensions. It's like a real-life game of Monopoly, but with less chance of losing your friends!