What Happens To Your Pension If You Die Before Retirement

So, You Died Before Retirement? Here's What Happens to Your Pension!
Alright, gather 'round, folks. Let's talk about something slightly morbid, but incredibly important. What happens to your pension if you kick the bucket before you can say "bingo wings"? Don't worry, I promise to keep it light and funny. After all, laughter is the best medicine, right? Unless you're laughing so hard you fall off your chair and break your hip. Then it's just a really expensive joke.
First Things First: It Depends on the Pension Plan
Picture this: You're sitting on your porch, rocking away, when suddenly, a squirrel runs up your leg, gives you a tiny heart attack, and bam! You're gone. Now, what happens to your pension? Well, it depends on the type of pension plan you've got.
If you've got a defined benefit plan, it's like having a personal pension fairy. You pay into it, and in return, the fairy promises to give you a certain amount of money every month when you retire. If you die before retirement, the fairy might give that money to your spouse or beneficiaries instead. But here's the kicker: some plans might make your spouse wait until they're 65 to get the full benefit. So, if your spouse is 60 and you die, they might have to wait five years for their pension party to start. Talk about a long engagement!
Must Read
Now, if you've got a defined contribution plan, it's like you're managing a little pension piggy bank. You put money in, and it grows (hopefully) thanks to investments. If you die, the money in your piggy bank goes to your beneficiaries. No waiting, no fairy games. It's like finding a surprise inheritance in your attic, but hopefully, without the creepy doll collection.
Beneficiaries: The Lucky (or Not So Lucky) Winners
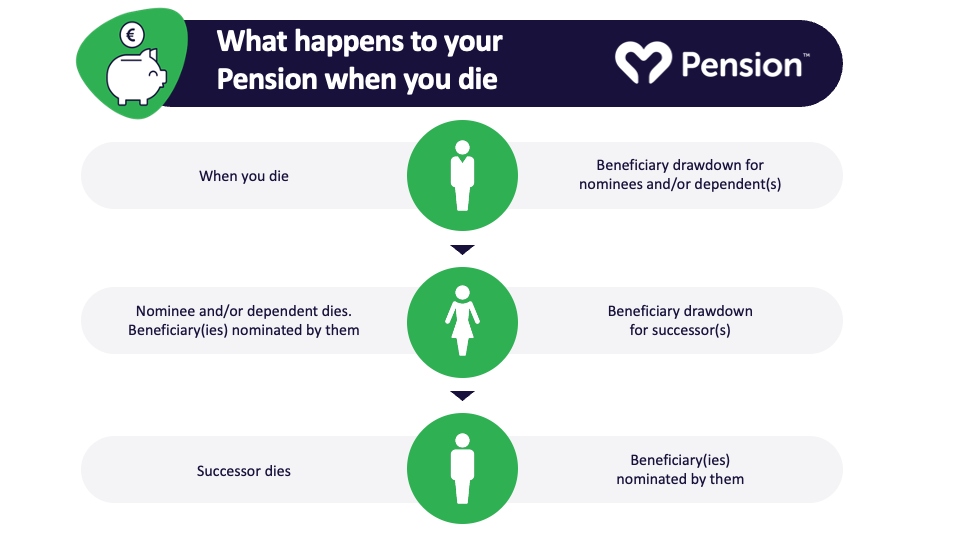
So, who are these mysterious beneficiaries? They're the people you've chosen to inherit your pension if you die. It could be your spouse, your kids, your best friend, or even your pet ferret. Just remember, if you choose your pet, make sure someone trustworthy will manage the money. A ferret might not be the best at handling finances, no matter how cute they are in a tiny tuxedo.
Now, here's where it gets interesting. If you haven't named a beneficiary, the pension money might go to your estate. And if you haven't written a will, your money could end up in some weird legal limbo. It's like a game of musical chairs, but with lawyers and money instead of music and chairs. Not exactly the fun kind of game, if you ask me.
Taxes: The Grim Reaper's Side Hustle
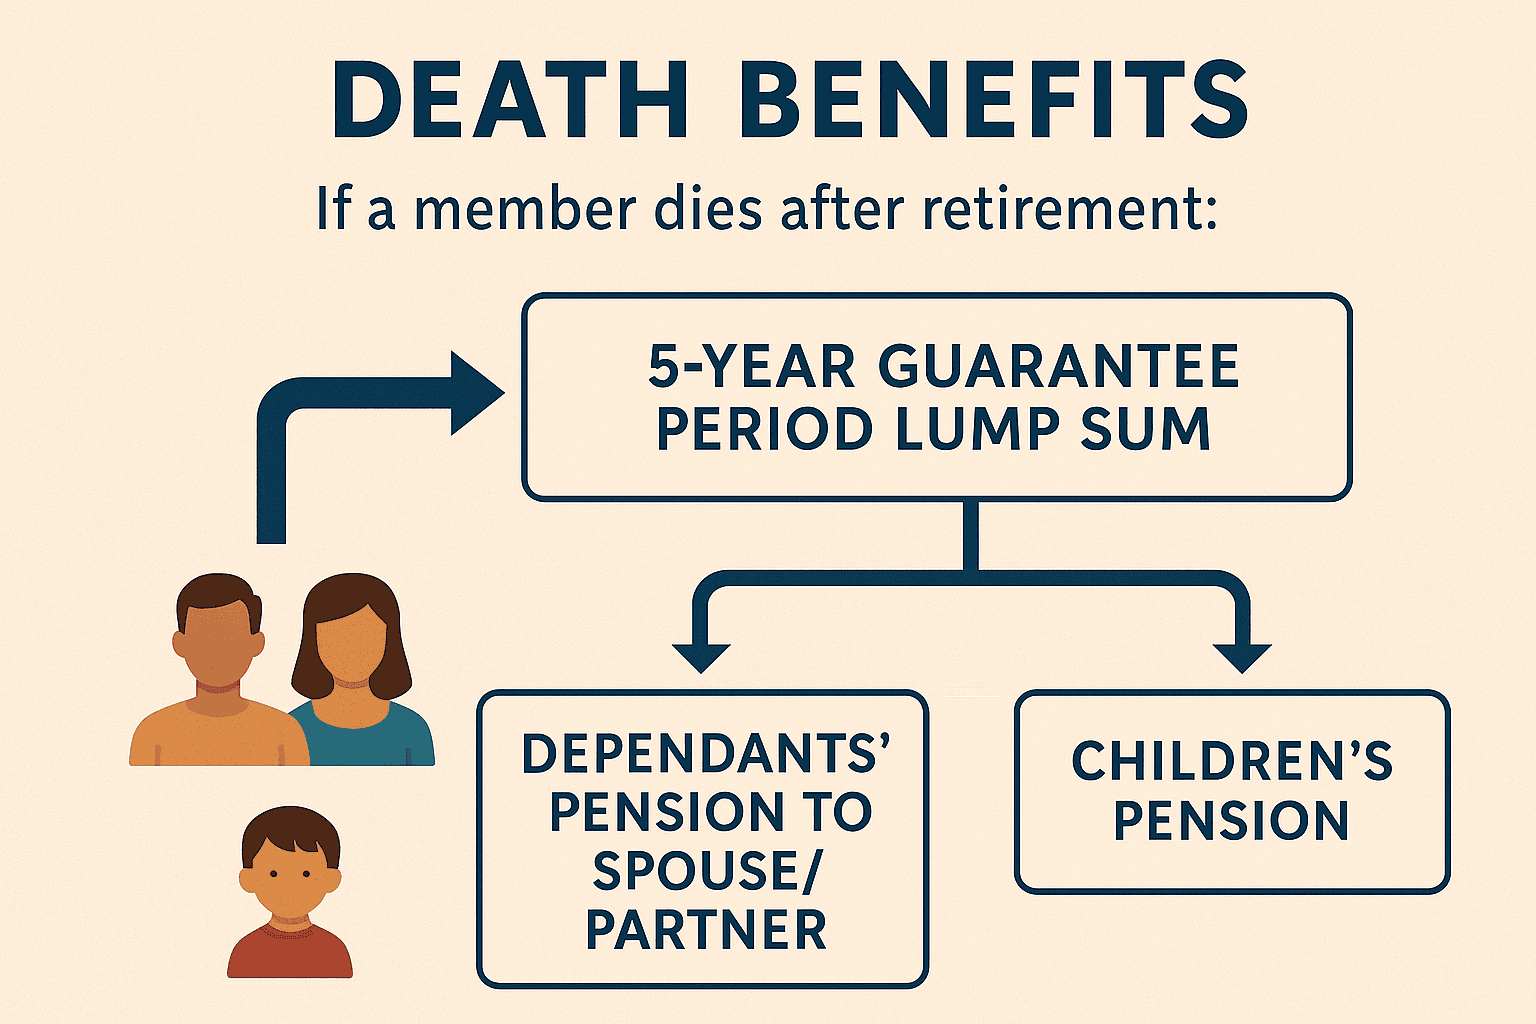
Death and taxes, right? Even after you're gone, the tax man cometh. How much tax your beneficiaries pay depends on the type of pension and when you die. If you die before you start receiving payments, your beneficiaries might not have to pay any taxes at all. It's like finding a loophole in the afterlife!
But if you die after you've started receiving payments, your beneficiaries will likely have to pay taxes on the money they inherit. It's not as fun as a tax refund, but hey, at least they'll have some money to spend on therapy to deal with the grief. Silver linings, folks!
So, What's the Moral of the Story?
First, don't die before retirement. It's just rude. Second, know what kind of pension plan you've got. It's like choosing between a surprise party and a surprise inheritance. Both can be exciting, but one might be better for your loved ones. Third, name a beneficiary. It's like choosing who gets your favorite chair when you're gone. You don't want your cat fighting with your dog over it, do you?
And finally, talk to your family about your pension. It's not the most fun conversation, but it's important. It's like talking about the birds and the bees, but with less awkwardness (hopefully) and more financial planning. So, grab a cup of tea, take a deep breath, and dive in. Your family will thank you (eventually). And who knows, you might even have some laughs along the way. Just don't laugh so hard you fall off your chair. Again.