
Vanguard Roth Ira Income Limits
Alright, gather 'round, folks. I've got a tale to tell about Roth IRAs and their income limits. Now, I know what you're thinking, "This sounds about as exciting as watching paint dry." But stick with me, I've got jokes, surprises, and a dash of financial wisdom that'll make you laugh and learn.
What's a Roth IRA?
First things first, let's get our terms straight. A Roth IRA is like your very own retirement piggy bank. You put money in, it grows over time, and when you're old and wise (and hopefully retired), you can take it out without the tax man knocking on your door.
Now, you might be thinking, "That sounds awesome! I'm in!" But hold your horses, because there's a catch. A big, fat, income limit catch.
Must Read
Income Limits? More Like Income Limits-BOO!
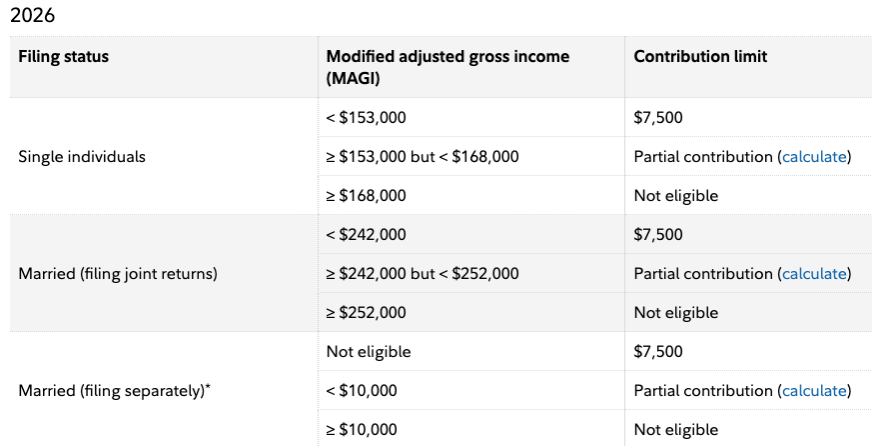
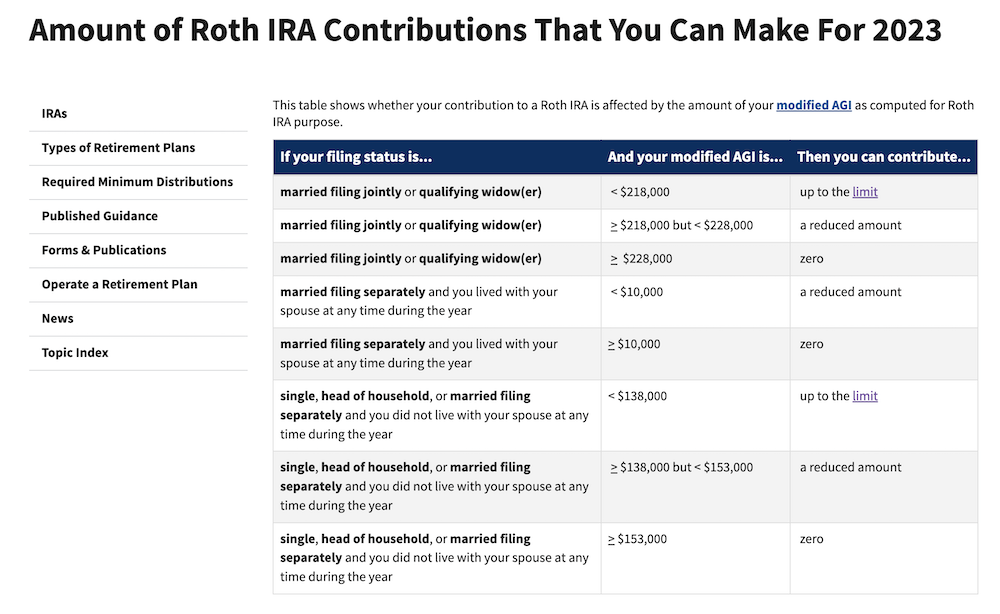
Imagine the income limits as a bouncer at an exclusive retirement party. It's got a list, and if your name (or rather, your income) isn't on it, you ain't getting in. For 2021, if you're single and filing taxes, you can't contribute to a Roth IRA if you make more than $140,000. And if you're married filing jointly, the limit is $208,000.
But don't worry, there's a loophole. If you're married filing separately, the limit is a mere $10,000. So, if you've got a high-flying spouse, you might want to consider filing separately. Just don't tell them I said that.
But Wait, There's More!
Now, if your income is just over the limit, don't despair. You can still contribute, but you'll need to do some financial contortionism. It's like trying to fit into your skinny jeans from college - it's possible, but it's gonna be a squeeze.
Here's where it gets a bit technical, but bear with me. If your income is above the limit but below the phase-out range, you can still contribute, but it'll be a partial contribution. And if your income is in the phase-out range, you can't contribute at all. It's like being in the friendzone - you're close, but not close enough.
Surprise! There's a Backdoor!
Alright, here's where things get interesting. If your income is too high to contribute directly to a Roth IRA, there's a sneaky way in - it's called a backdoor Roth IRA. It's like finding a secret entrance to your favorite club. Here's how it works:

You contribute to a traditional IRA (which has no income limits), then you convert that money into a Roth IRA. Voila! You've snuck in the backdoor. But be warned, there are some tax implications, so you might want to consult a financial advisor. Or at least a really smart friend.
So, What's the Moral of the Story?
Alright, folks, I've taken you on a wild ride through the world of Roth IRAs and their income limits. The moral of the story? Retirement savings can be complex, but they don't have to be boring. And if you're feeling overwhelmed, don't be afraid to ask for help. After all, the future you will thank you.
And remember, whether you're contributing to a Roth IRA or not, every little bit helps when it comes to retirement. So, start saving, folks. Your future self is counting on you.