Is It Better To Overpay Mortgage Or Reduce Term
So, you're sitting there, sipping your coffee, staring at that mortgage statement, and wondering, "Should I chuck more money at this beast or just keep it on the current plan?" Let's dive into the great debate: overpay or reduce term?
Overpay: The Snowball Effect
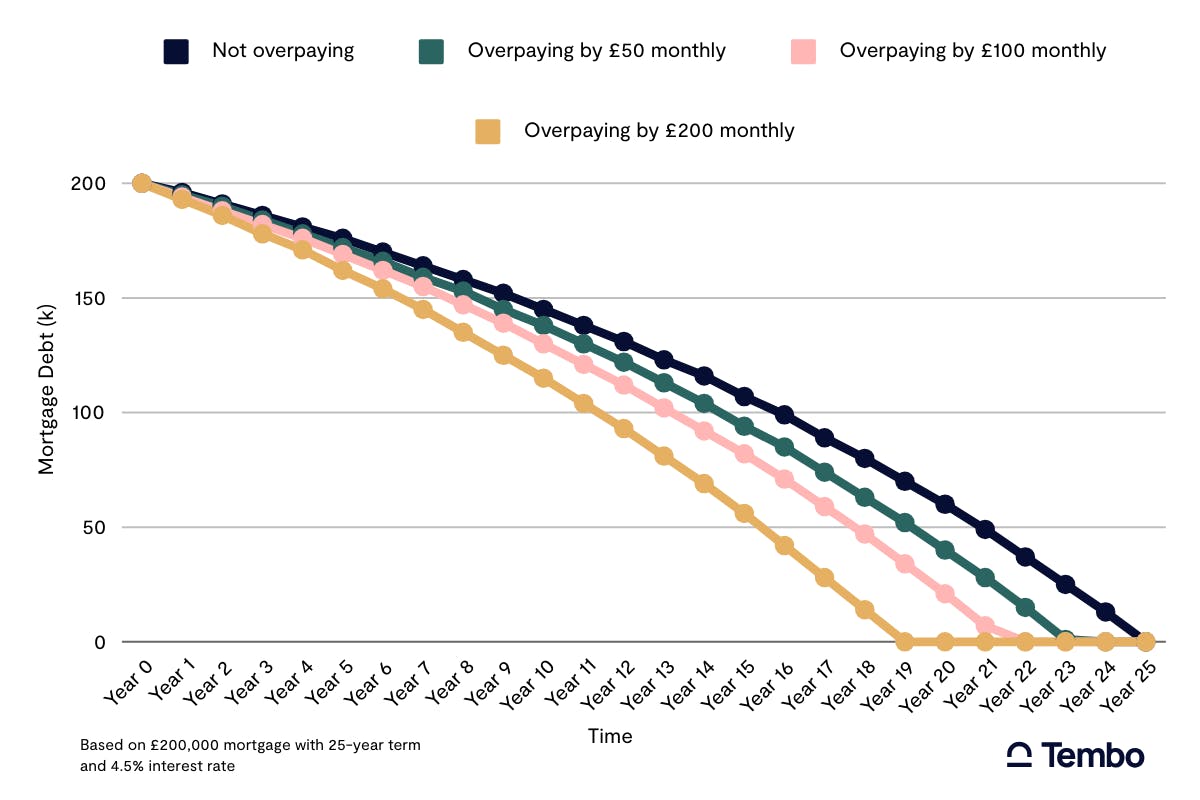
Imagine you're rolling a snowball down a hill. The more it grows, the faster it goes, right? That's kinda like overpaying your mortgage. Each extra dollar you throw at it reduces your principal, which in turn reduces the interest you pay. It's like watching your debt shrink in fast-forward.
But here's the thing, you have to be the one to keep that snowball rolling. It's not like the bank's going to call you up and say, "Hey, you're paying too slow! Let's speed this up!" Nope, it's all on you, buddy.
Must Read
Pros of Overpaying
- Save on Interest: The more you pay off, the less interest you pay. It's math, folks.
- Pay Off Faster: You could shave years off your mortgage. That's like getting a time machine, but for debt.
- Flexibility: If you overpay, you can always ask the bank to put that extra cash back into your pocket if you need it. Just don't count on it until it's done.
Reduce Term: The Race Against Time
Now, picture yourself in a race. You've got a set distance to cover, and you want to finish as fast as possible. That's reducing your term. You're paying the same amount each month, but you're cramming it into a shorter time frame.
This one's all about discipline, though. You've got to stick to that plan, no matter what. It's like training for a marathon, but with less lycra.
Pros of Reducing Term
- Pay Less Interest: The shorter your term, the less time your money has to collect interest. It's like outrunning a bear, but with numbers.
- Freedom: The sooner you're done, the sooner you can do whatever you want with that money. No more mortgage payments means more money for, well, whatever you want.
- Peace of Mind: There's something to be said for knowing you'll be debt-free in, say, 15 years instead of 30. It's like having a superpower, but for your bank account.
So, Which One's Better?
Well, that depends on you, my friend. If you're all about the long game and want to see your debt shrink, overpaying might be your jam. But if you're more of a "get 'er done" kind of person, reducing your term could be the way to go.

Here's the thing, though: either way, you're making progress. You're not just sitting there, letting that debt pile up. You're doing something about it. And that, my friend, is something to be proud of.
So, grab another cup of coffee, think about it some more, and then make your move. Your future self will thank you, I promise.