
How To Build Credit Without A Credit Card
So, you're ready to dive into the world of credit, but the thought of swiping a plastic card has you saying, "Not today, Satan." We get it. Credit cards can be a slippery slope to debt city, and you're not about that life. But fear not, dear friend, for there are other ways to build credit, and we're here to spill the tea.
First Things First: What's This Credit Score Business?
Your credit score is like your financial report card. It's a three-digit number that lenders use to decide if you're credit-worthy. The higher your score, the more likely you are to get approved for loans, credit cards, and even apartments. It's a big deal, and it's time to start building yours.
Step 1: Become an Authorized User
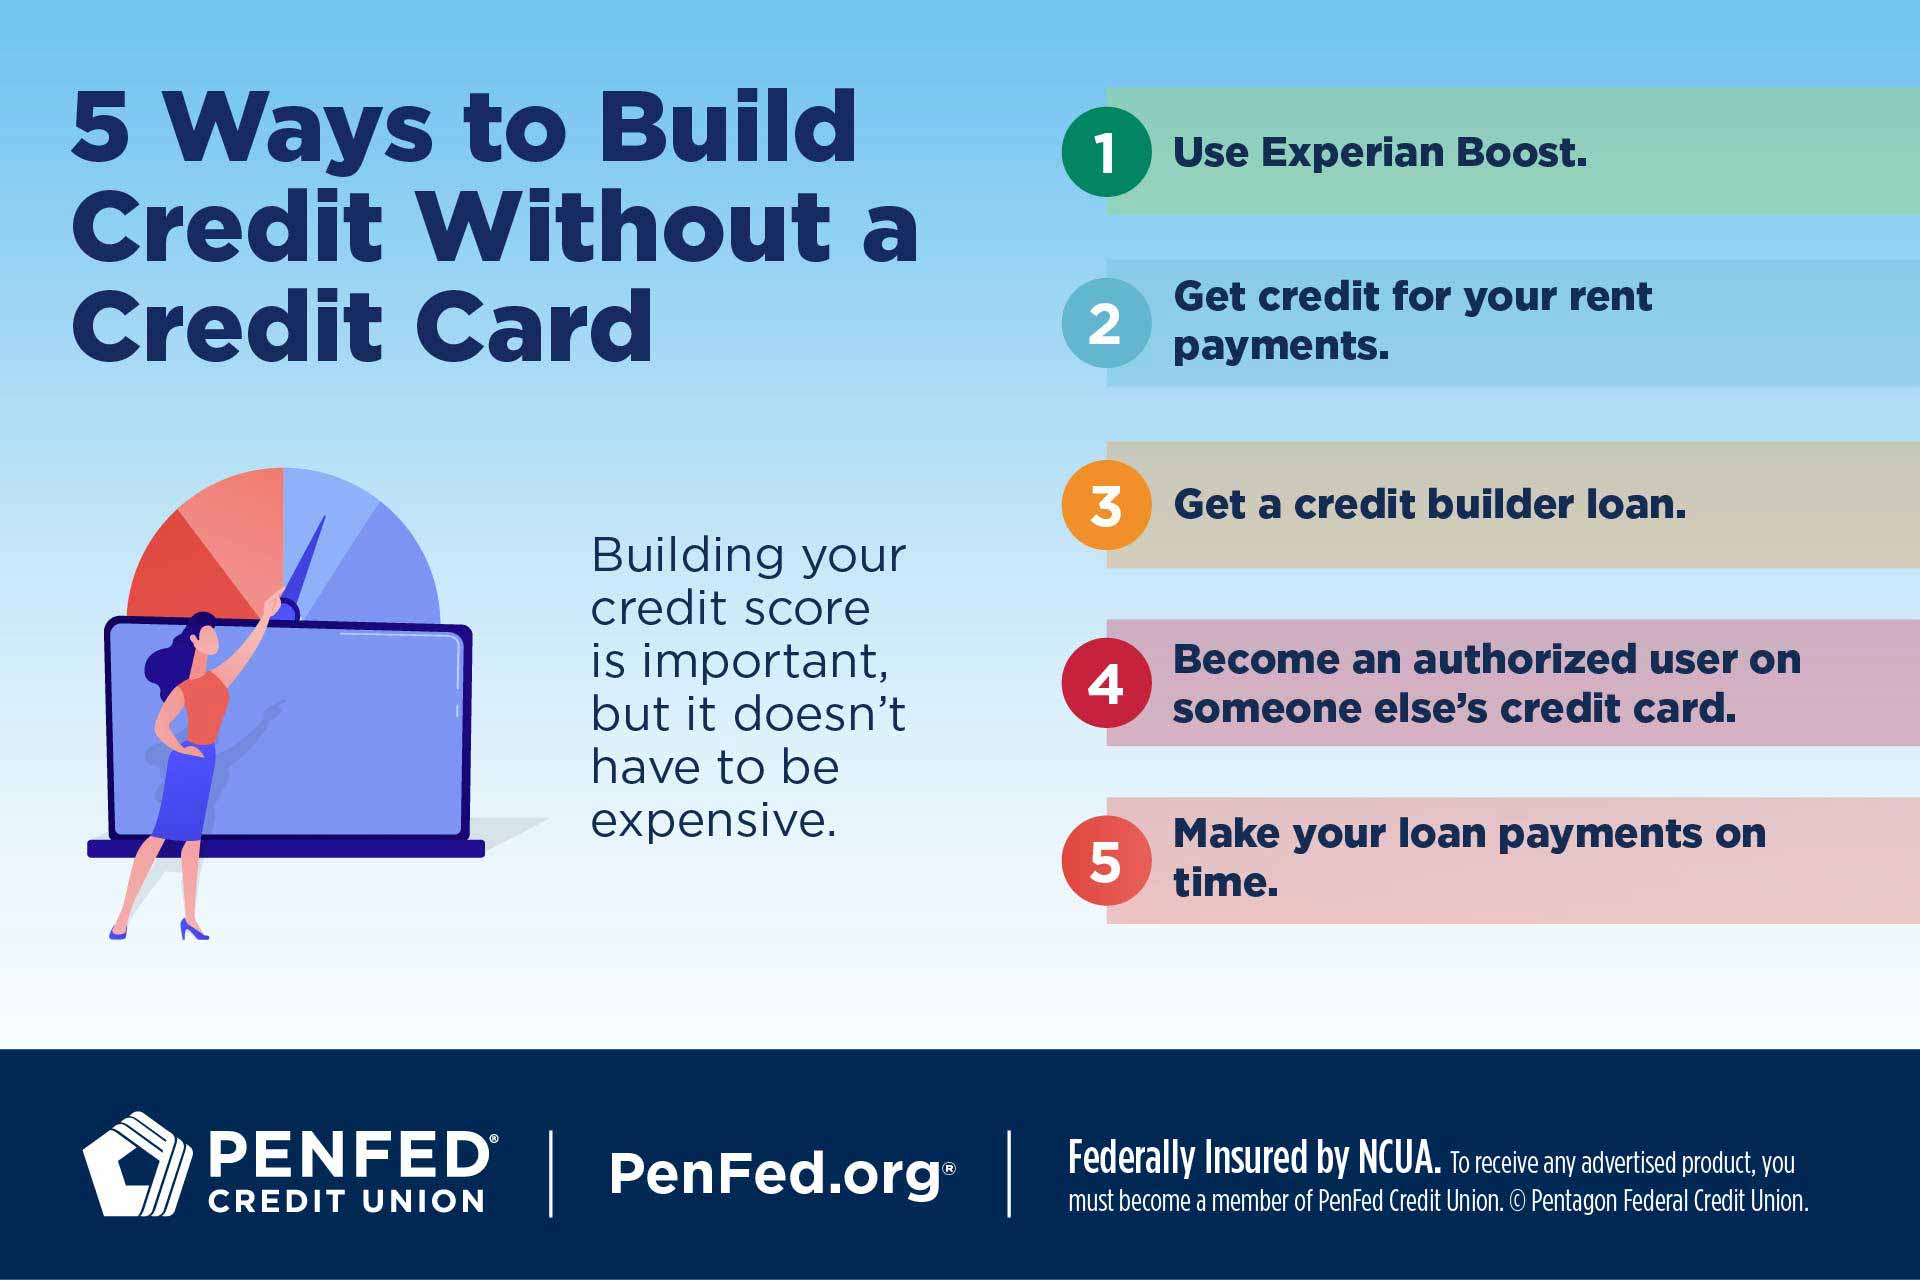
Ever heard of being an authorized user? It's like being a plus-one to the credit party. You can become one on someone else's credit card, like a parent or a trusted friend. They add you as an authorized user, and their good credit history can boost your score. Just remember, you won't be responsible for payments, but you can still use the card. So, don't go on a shopping spree and leave them hanging.
Must Read
Fun Fact:
Did you know that 26% of Americans have no credit or bad credit? You're not alone in this credit-building journey.
Step 2: Get a Secured Credit Card
A secured credit card is like training wheels for credit. You put down a security deposit, usually around $200, and that becomes your credit limit. You use the card like a regular one, but with a safety net. Make sure to pay off your balance in full each month to build a solid payment history.
Pro Tip:
Choose a secured card that reports to all three major credit bureaus (Equifax, Experian, and TransUnion) to maximize your credit-building potential.
Step 3: Take Out a Credit-Builder Loan
Credit-builder loans are designed for, well, building credit. You borrow a small amount, usually around $300 to $1,000, and the lender holds the money in a savings account while you make payments. Once you've paid it off, the lender releases the funds to you. It's like a savings account and a credit-builder in one.
Step 4: Pay Your Bills on Time
Your payment history makes up 35% of your credit score, so it's crucial to pay your bills on time. This includes utilities, rent, and even your Netflix subscription. Some companies don't report to the credit bureaus, but you can use services like Experian Boost to get credit for these payments.
Cultural Reference:
Remember the episode of "Friends" where Monica and Rachel argue about who's responsible for the rent? Don't be like them. Set up automatic payments to ensure you never miss a bill.

Step 5: Keep Your Credit Utilization Low
Credit utilization is the amount of credit you're using compared to your total credit limit. Aim to use less than 30% of your available credit. For example, if your credit limit is $1,000, try not to charge more than $300 at a time. This shows lenders that you're responsible with credit.
Reflection: Credit-Building is a Marathon, Not a Sprint
Building credit takes time, and it's easy to get discouraged when you don't see immediate results. But remember, every on-time payment and every responsible credit decision is a step in the right direction. It's like training for a marathon. You don't go from couch potato to ultra-marathoner overnight. You start with small steps, and before you know it, you're crossing that finish line with a shiny new credit score.
So, keep at it. Check your credit report regularly (you can get a free one from each of the three major credit bureaus once a year at AnnualCreditReport.com). Celebrate your progress, learn from your mistakes, and most importantly, stay committed to your credit-building journey.
You got this. Now go forth and build that credit, one responsible step at a time.