
Help To Buy Or Shared Ownership
So, picture this: You're strolling through the local estate agent's window, dreaming of that perfect 'Home Sweet Home' sign, when you spot it - the one that's got 'Help to Buy' or 'Shared Ownership' plastered all over it. You're thinking, "What's that all about then?" Well, grab a cuppa, let's chat about it.
Help to Buy - The 'I Can't Believe It's Not Mortgage' Scheme
Alright, so you're dreaming of a house, but the prices are sky-high, and your savings are looking more like a piggy bank than a war chest. That's where Help to Buy comes in, like the fairy godmother of homeownership.
Here's the skinny: You only need a 5% deposit, and the government lends you up to 20% (40% in London) of the cost of a new build home, interest-free for the first five years. Then, you only need a mortgage for the rest. It's like magic, right? But remember, you're still borrowing money, so it's not all rainbows and unicorns.
Must Read
Shared Ownership - The 'I'll Have What She's Having' Option
Now, let's say you're looking at a house, but it's still a bit out of reach. That's where Shared Ownership steps in, like the bestie who's always got your back.
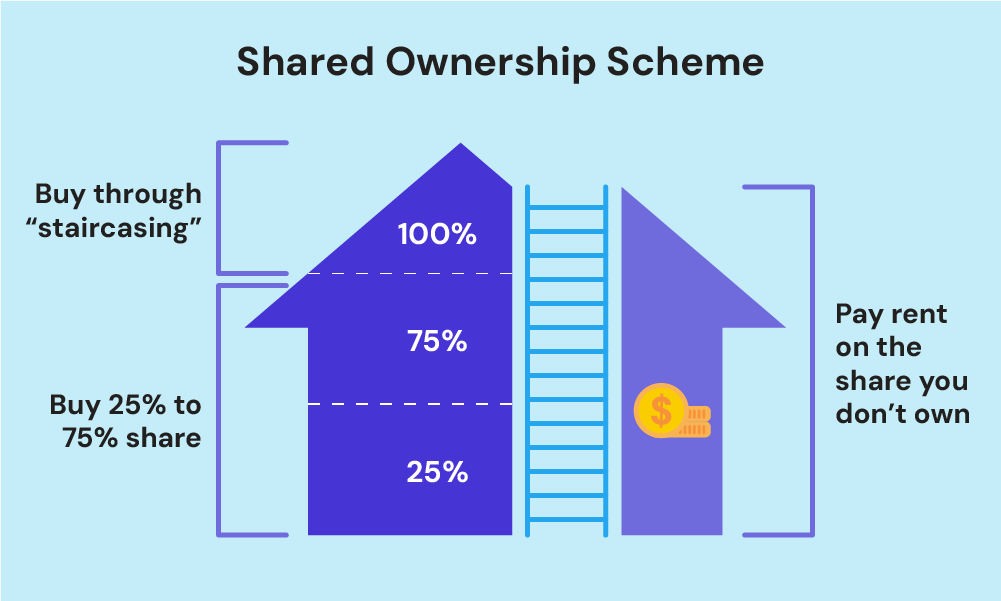
With Shared Ownership, you buy a share of a home (between 25% and 75%), and a housing association owns the rest. You only need a mortgage for your share, and you pay rent on the rest. It's like having a roommate, but with a house instead of a dorm room. And the best part? You can buy more shares later if you fancy it.

But hold your horses, there's a catch. You'll need to be earning less than £80,000 a year (or £90,000 in London), and you'll need to save for a deposit too. Plus, you'll need to be approved by the housing association. It's not a free-for-all, but it's still a great option for many.
So, Which One's for You?
Well, that depends on your situation. If you've got your heart set on a new build and can afford a mortgage, Help to Buy might be your jam. But if you're after an older home or can't quite stretch to a mortgage, Shared Ownership could be the way to go.

And remember, both schemes have their pros and cons. You're still borrowing money, and there are fees involved. But if you're struggling to get on the property ladder, they could be the boost you need.
So, there you have it, the lowdown on Help to Buy and Shared Ownership. Now, go forth and conquer that property market!