
Fidelity Roth Ira How To Invest
Let's Get Rich(ish) with a Roth IRA: A Fun Guide
Alright, gather 'round, my fellow coffee-sippers and aspiring millionaires. Today, we're going to tackle something that sounds about as exciting as a trip to the DMV: investing in a Roth IRA. But don't worry, I promise to keep it as painless and entertaining as possible. Who knows, you might even laugh a little (or at least smile politely).
First Things First: What's a Roth IRA?
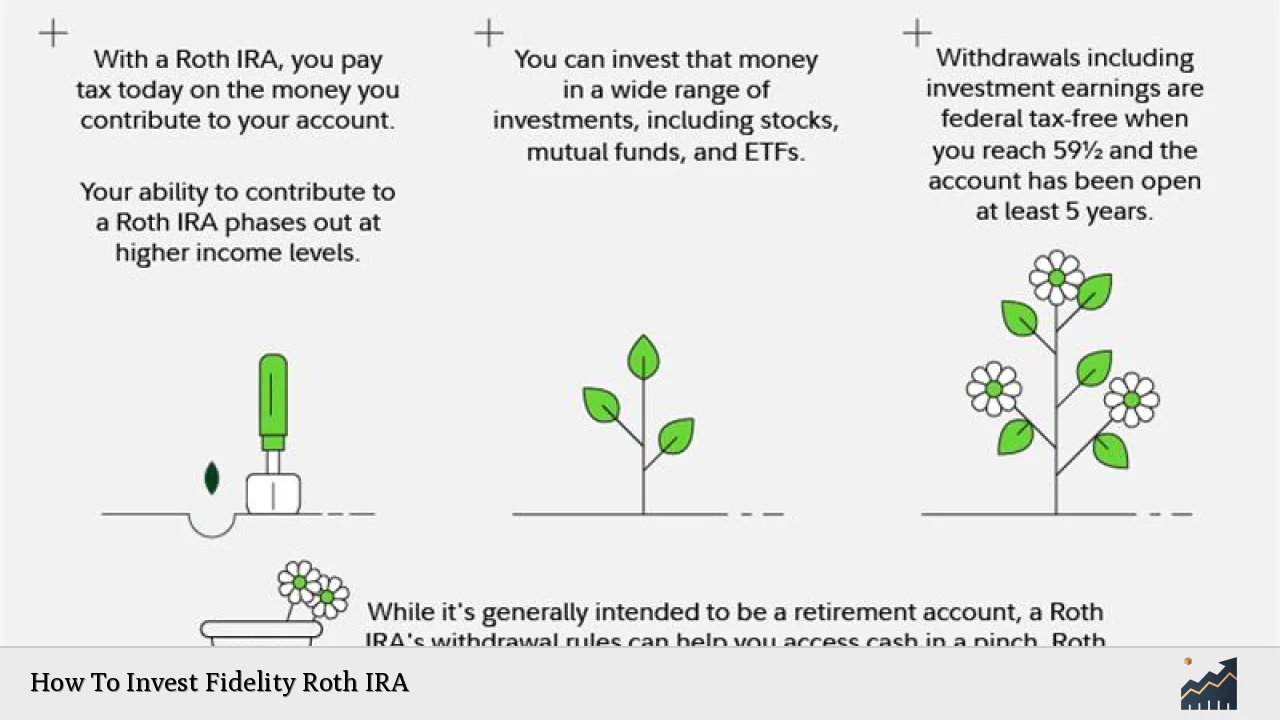
Imagine a Roth IRA as a magical piggy bank that grows your money like a tiny, financial chia pet. It's a retirement account where you contribute after-tax dollars, meaning you pay your taxes upfront. In return, your money grows tax-free, and when you retire, you can withdraw it without any tax worries. It's like a secret handshake with the IRS.
Now, you might be thinking, "That sounds amazing! Why isn't everyone doing this?" Well, my friend, there are some rules. You can't contribute to a Roth IRA if you make too much money (sorry, billionaires). And there are limits to how much you can contribute each year. But don't worry, the limits are high enough that even us mere mortals can play the game.
Must Read
How Much Can You Contribute?
In 2022, you can contribute up to $6,000 if you're under 50, or $7,000 if you're 50 or older. That's right, the older you get, the more the government lets you stuff into your piggy bank. It's like they're rewarding us for surviving another year on this crazy planet.
But here's where it gets interesting: you can open a Roth IRA at any age, as long as you have earned income. That means if you're a teenager working at the local ice cream shop, you can start investing for your retirement. Isn't that adorable? You're basically planning for your future while scooping cones. Talk about multitasking.
Now, Let's Talk Investing
So, you've opened your Roth IRA and you're ready to dive in. But where do you put your money? That's where things can get a little... complicated. But don't worry, I've got you. Let's break it down into baby steps.
Step 1: Choose a Roth IRA Provider
First things first, you need a place to park your money. There are tons of options out there, from big banks to online brokers. Some are fancy and schmancy, with all the bells and whistles. Others are simple and straightforward. The key is to find one that fits your needs and doesn't charge an arm and a leg in fees.
Personally, I'm a fan of online brokers. They're usually cheaper, and they make it super easy to open an account and start investing. Plus, they often have helpful tools and resources to guide you along the way. It's like having a financial cheerleader in your corner.
Step 2: Decide on Your Investments
Alright, now comes the fun part: picking what to invest in. This is where a lot of people get stuck, because there are so many options. Stocks, bonds, mutual funds, ETFs, cryptocurrency... it's enough to make your head spin.
Here's a little secret: you don't need to know everything about every investment out there. In fact, trying to do so can often lead to analysis paralysis. So, let's keep it simple.
First, consider low-cost index funds or exchange-traded funds (ETFs). These are basically big baskets of stocks or bonds that track a specific market index. They're super diversified, which means you're not putting all your eggs in one basket. And they're usually cheap to buy and own, which is always a plus.
Another option is target-date funds. These are mutual funds that automatically adjust their asset mix to become more conservative as you get closer to retirement. It's like having a financial robot that grows up with you. Creepy? Maybe. Convenient? Definitely.
And if you're feeling fancy, you might consider a robo-advisor. These are automated investment services that use algorithms to manage your portfolio. They ask you a bunch of questions about your risk tolerance and financial goals, then they do all the heavy lifting for you. It's like having a financial butler. Who wouldn't want one of those?
Step 3: Diversify, Diversify, Diversify
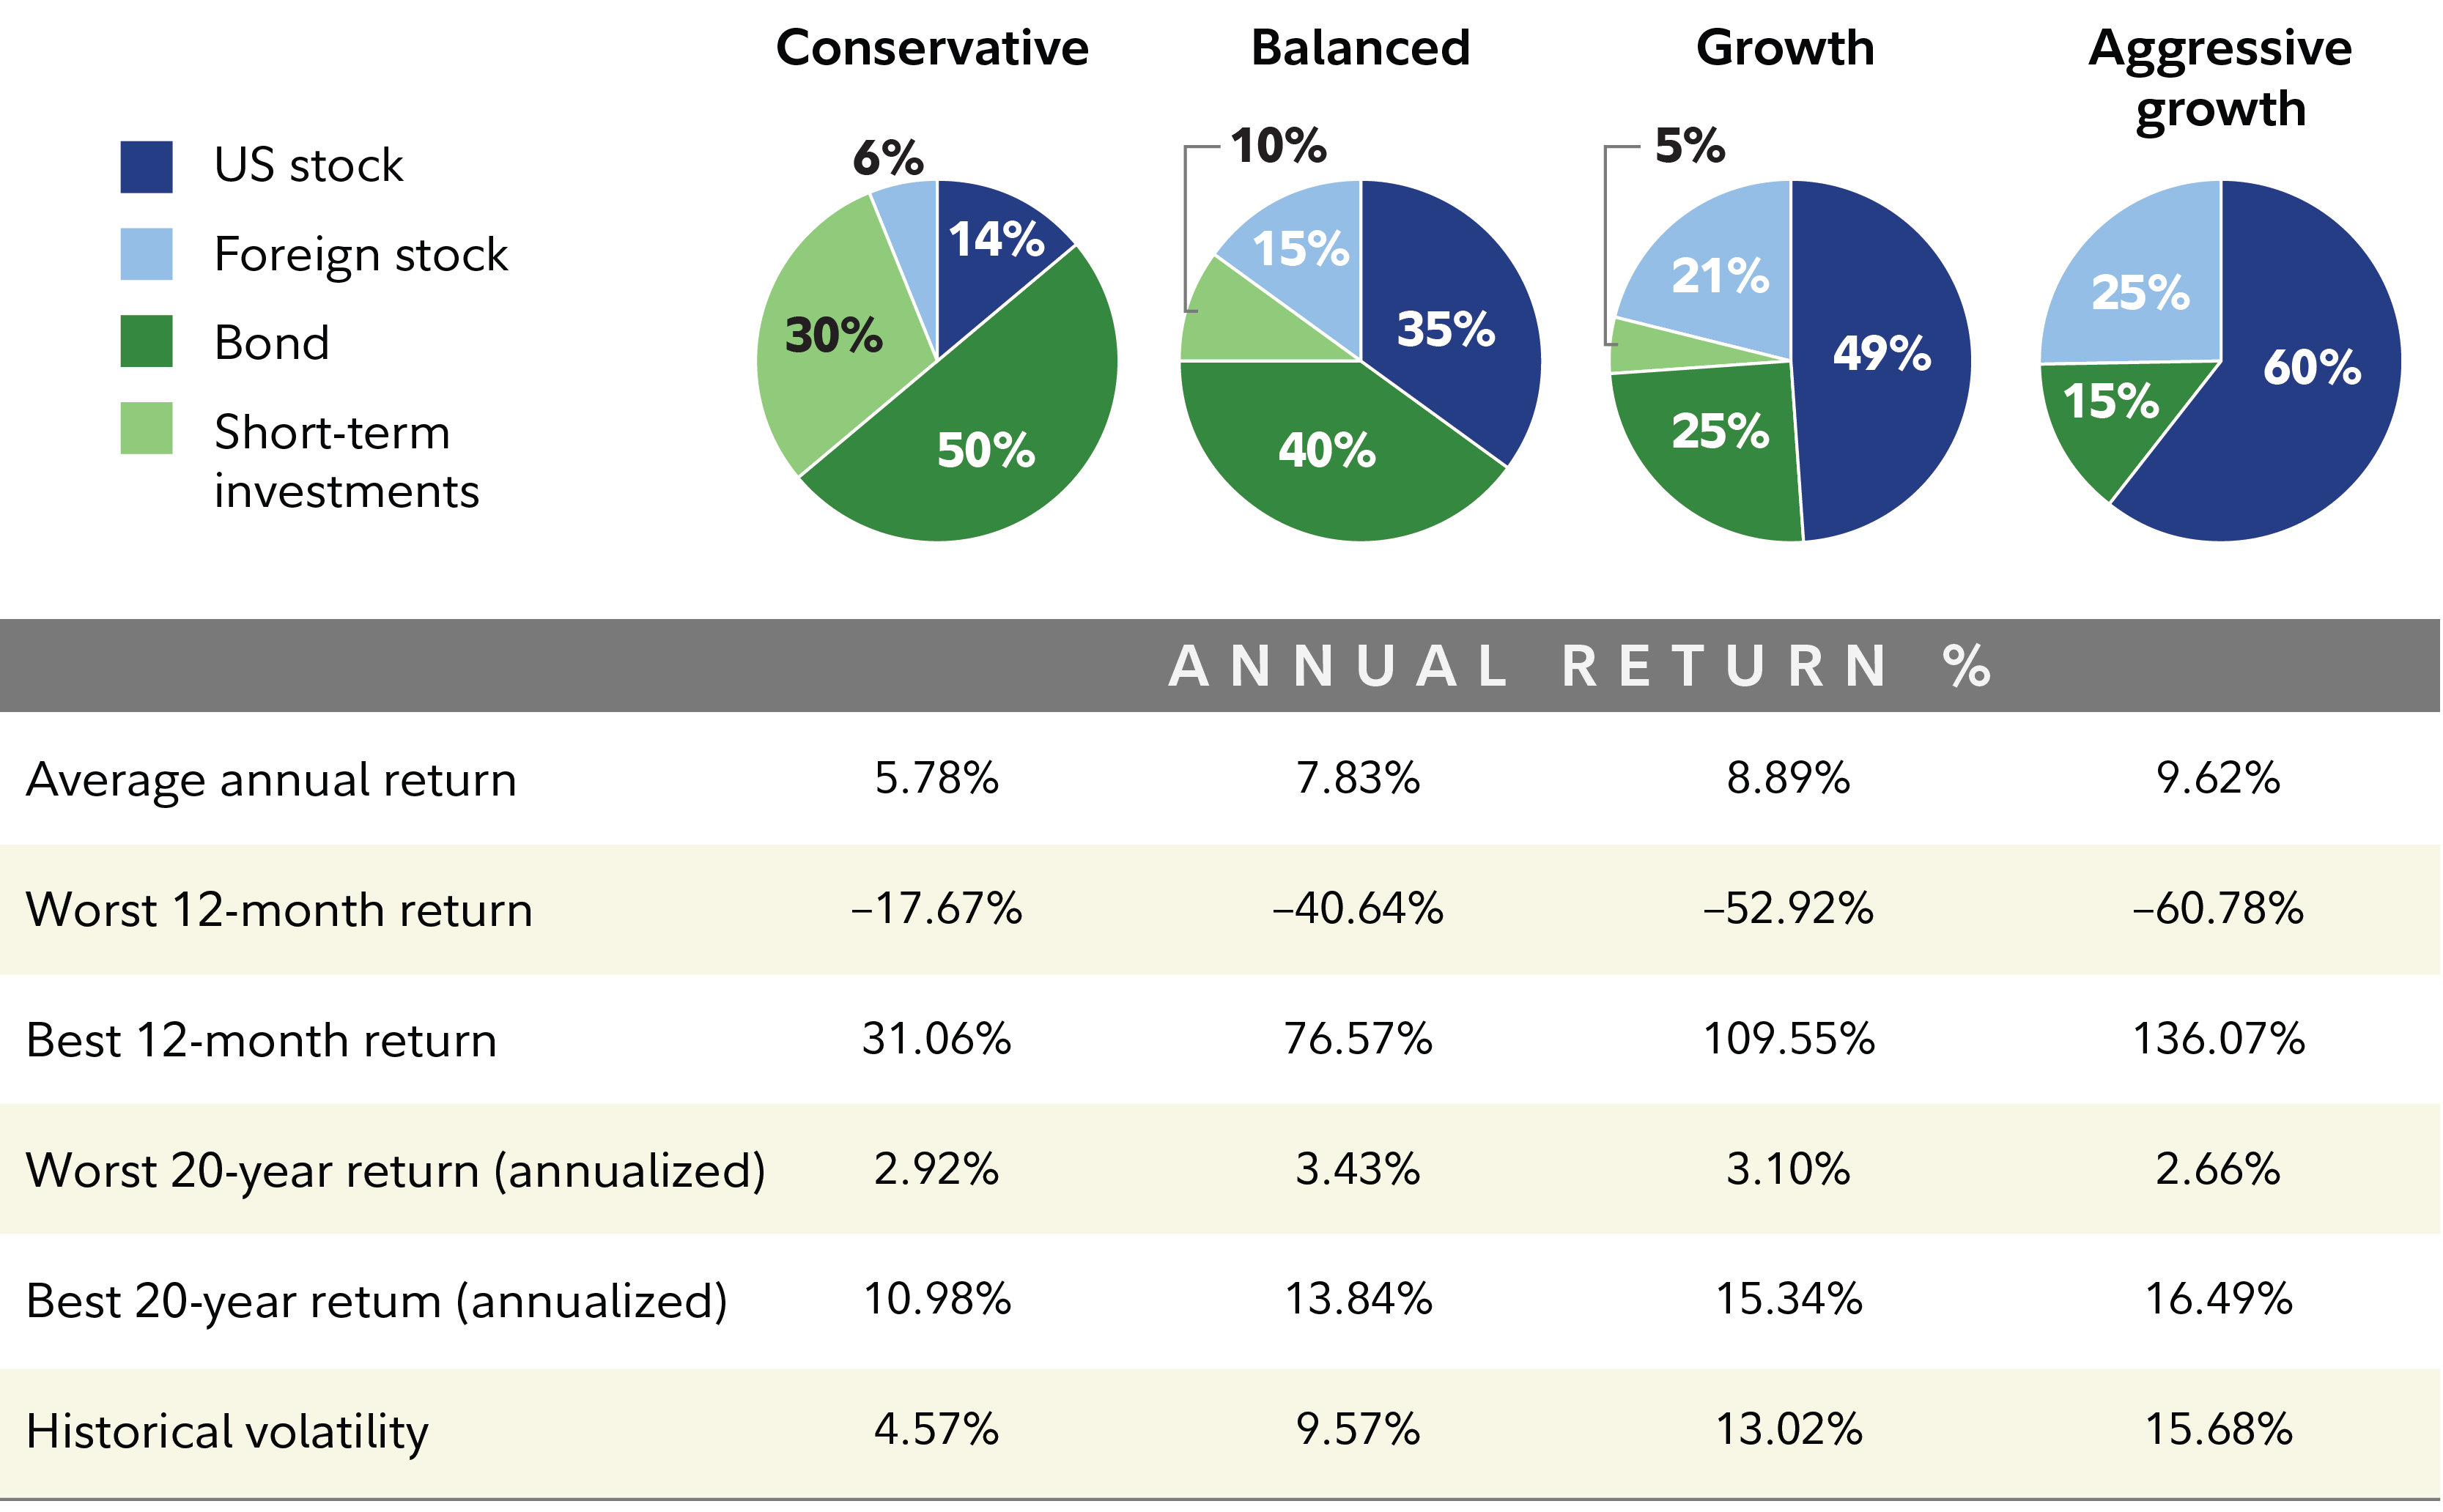
Remember what your mom always told you: don't put all your eggs in one basket. The same goes for investing. You want to spread your money around so that if one investment tanks, you're not completely screwed.

This is where asset allocation comes in. That's just a fancy way of saying, "Don't put all your money in tech stocks just because you love your iPhone." You want a mix of stocks, bonds, and maybe even some alternative investments like real estate or commodities.
Here's a fun fact: the average millionaire has 7 sources of income. Seven! That's like having seven little money-making machines. So, diversify not just within your Roth IRA, but also outside of it. Start a side hustle, invest in real estate, or even just put some money in a high-yield savings account. The more streams of income you have, the richer you become. It's like building your own personal money river.
But What About...?
I know, I know, I've barely scratched the surface. There are so many more questions you might have: What about Roth IRA conversion? What about the Roth IRA 5-year rule? What about the dreaded Roth IRA contribution limit?
Don't worry, we'll tackle all that in another coffee-fueled adventure. For now, let's just focus on the basics. You've got your Roth IRA opened, you've contributed some money, and you've invested it wisely. You're officially on your way to retirement riches!
So, go forth, young investor. Make your money work for you. And remember, the best time to start investing was yesterday. The second best time is today. So, what are you waiting for? Get out there and make your money grow!
And if all else fails, you can always just invest in coffee. After all, a dollar spent on coffee is a dollar well spent, right? Right? Hello? Anyone still there?