Detail Unitedhealthcare Plan Benefits Regarding Essential Medical Coverage

Alright, folks, let's dive into the world of UnitedHealthcare plans and their essential medical coverage. Now, I know what you're thinking, "Boring! I'd rather watch paint dry." But hold your horses, because we're going to spice things up and make this as interesting as a trip to the ice cream parlor on a hot summer day.
So, What's the Deal with These Essential Plans?
Imagine essential plans as the trusty old sedan in your garage. It might not be a flashy sports car, but it gets you from point A to point B without breaking the bank. In the world of health insurance, that's exactly what essential plans do. They cover the basics, the must-haves, the things you can't live without (well, not literally, but you know what I mean).
Mandatory Coverage: The Three Musketeers
Now, these plans have to cover three key areas, and they're so important that the government made them mandatory. I like to think of them as the Three Musketeers of healthcare: ambulatory patient services (that's fancy talk for outpatient care), emergency services (because accidents happen, and you need to be covered), and hospitalization (because sometimes, you just need to kick back and let the professionals take care of you).
Must Read
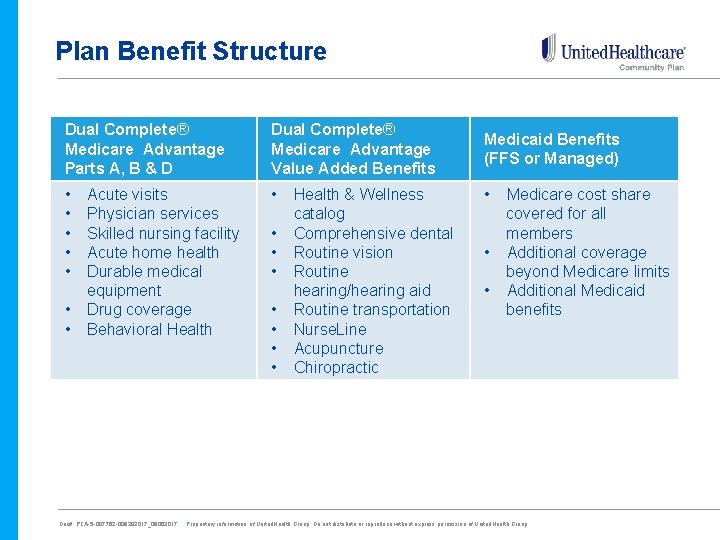
But wait, there's more! These plans also cover things like preventive and wellness services (think: regular check-ups and flu shots), prescription drugs (because nobody likes to pay an arm and a leg for medicine), and laboratory services (because sometimes, you need to get your blood tested, and that's not something you want to DIY).
Out-of-Pocket Maximums: The Safety Net
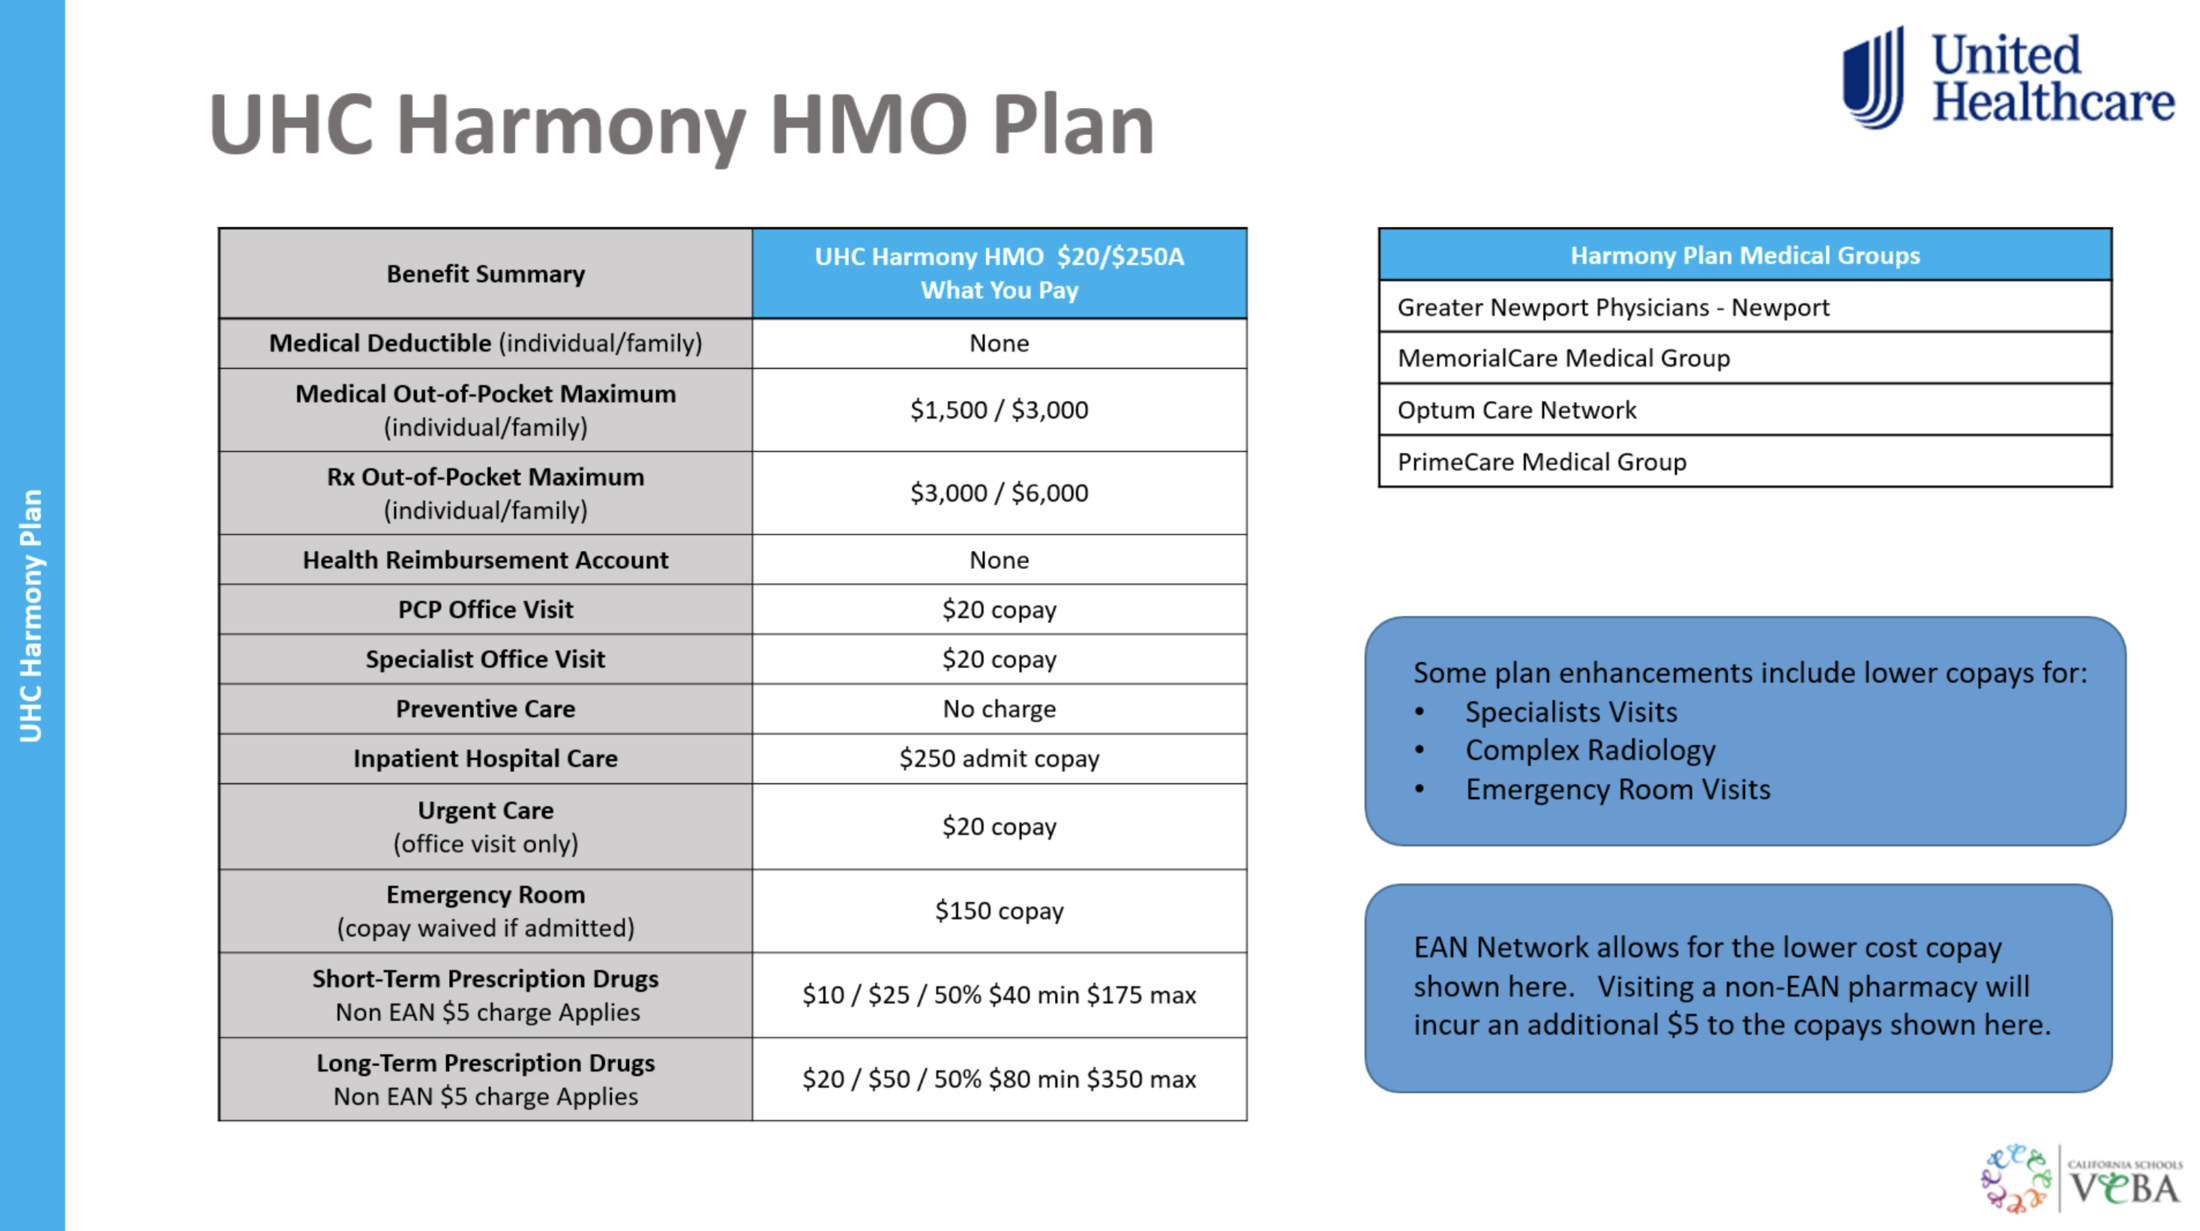
Now, let's talk about out-of-pocket maximums. Imagine you're at a buffet (because who doesn't love a good buffet?), and you've got a set amount of money to spend. Once you hit that limit, you're done. That's basically what out-of-pocket maximums do. They're the safety net that catches you when you've spent enough on healthcare for the year. Once you hit that limit, UnitedHealthcare picks up the tab for the rest of the year. It's like having a personal finance fairy godmother.
But What About the Fancy Stuff?
Alright, so essential plans cover the basics, but what about all the extra bells and whistles? Well, that's where the optional plans come in. Think of them as the luxury upgrades at the car dealership. You can add on things like dental, vision, or even maternity coverage. But remember, these upgrades come at an extra cost, just like that fancy leather interior or sunroof.
Now, you might be thinking, "This all sounds great, but I don't want to break the bank." Well, my friend, that's where the magic of deductibles, copays, and coinsurance comes in. It's like a choose-your-own-adventure book, where you can pick the option that fits your budget. Just remember, the lower the deductible, the higher the monthly premium, and vice versa. It's a balancing act, my friends, a delicate dance between affordability and coverage.
So, Should You Jump On Board?
Well, that depends on you. If you're a risk-taker, the kind of person who likes to live on the edge, you might be tempted to skip out on health insurance altogether. But remember, life is full of surprises, and sometimes those surprises come with a hefty price tag. Health insurance is like having a financial safety net, a parachute that cushions the fall when things go wrong.
So, before you make a decision, think about your health, your lifestyle, and your budget. Talk to the experts at UnitedHealthcare, ask questions, and weigh your options. Because at the end of the day, it's your health we're talking about, and that's something worth investing in.
And there you have it, folks. UnitedHealthcare plans demystified. Now, go forth, make an informed decision, and remember: health insurance might not be as exciting as a roller coaster ride, but it's a whole lot more important. Stay healthy, stay happy, and until next time!